Business Operations
\nNSSA Dual-Currency Contributions and APWCS: Complete Guide to USD Priority, Ceiling Allocation and Payroll Processing
\nNSSA Dual-Currency Contributions and APWCS: Complete Guide to USD Priority, Ceiling Allocation and Payroll Processing Introduction Zimbabwe’s multi-currency payroll environment requires employers to administer two separate NSSA schemes: Pension and Other Benefits Scheme (POBS)…
\n\nNSSA Dual-Currency Contributions and APWCS: Complete Guide to USD Priority, Ceiling Allocation and Payroll Processing
Introduction
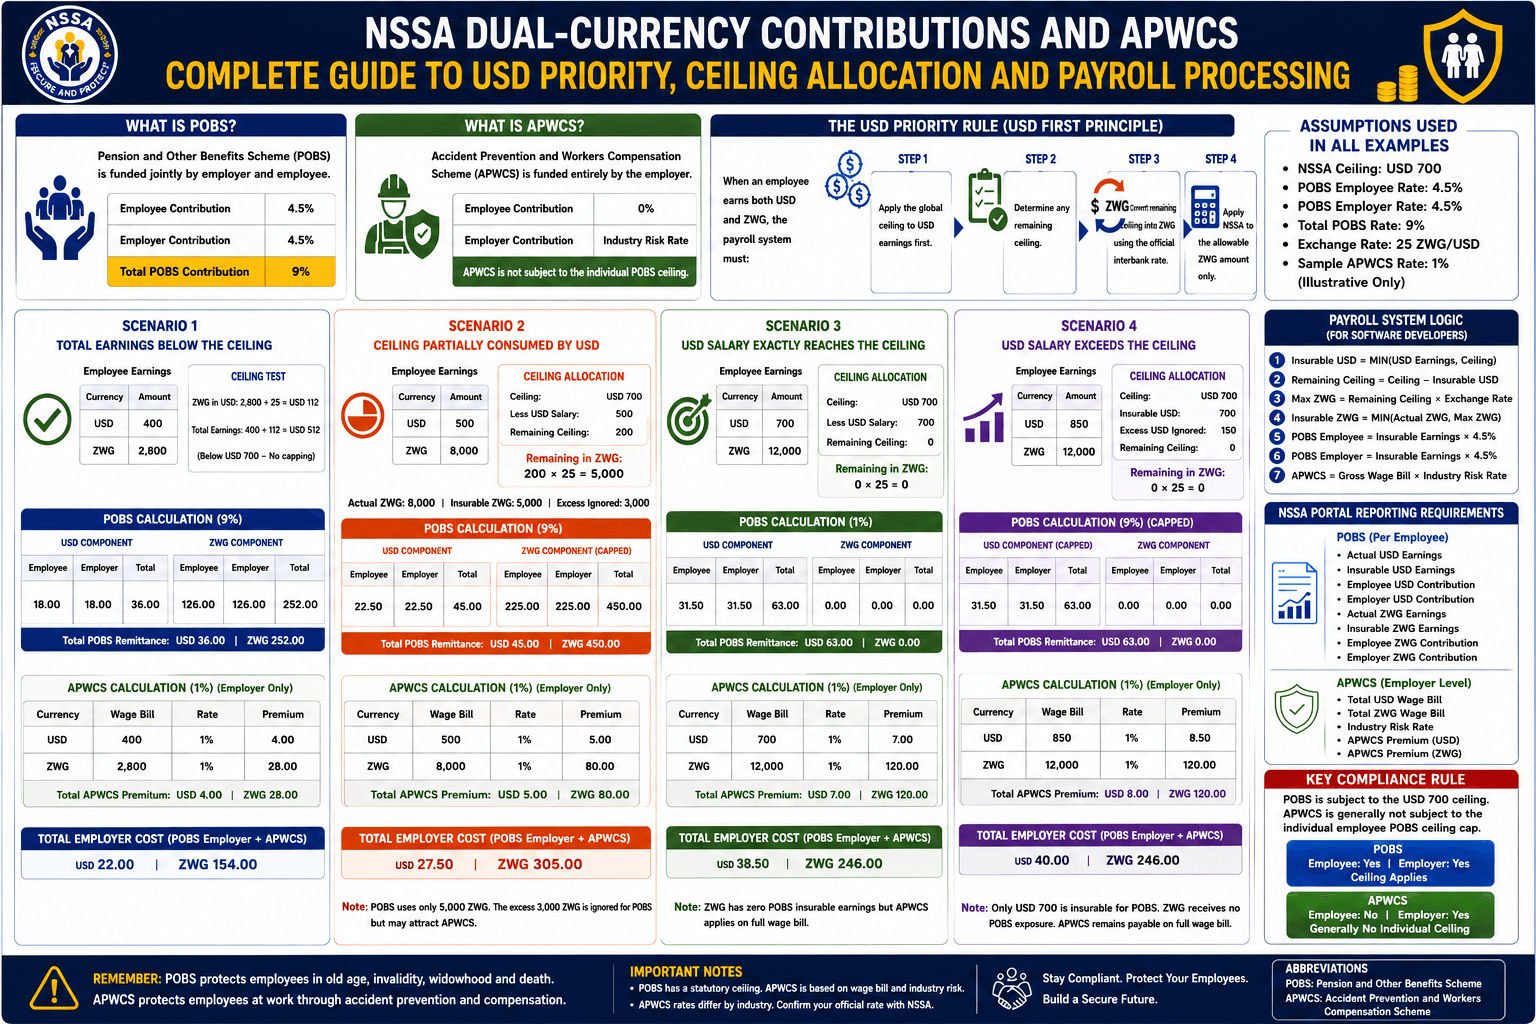
Zimbabwe’s multi-currency payroll environment requires employers to administer two separate NSSA schemes:
Pension and Other Benefits Scheme (POBS)
POBS is funded jointly by employer and employee.
| Contributor | Rate |
|---|---|
| Employee | 4.5% |
| Employer | 4.5% |
| Total | 9% |
POBS is subject to the NSSA statutory earnings ceiling.
Accident Prevention and Workers Compensation Scheme (APWCS)
APWCS is different.
| Contributor | Rate |
|---|---|
| Employee | 0% |
| Employer | Industry Risk Rate |
APWCS:
- Is funded entirely by the employer.
- Is based on the employer’s registered industry risk category.
- Is generally assessed on the wage bill.
- Is not governed by the same individual employee POBS ceiling mechanism.
This distinction becomes critical when processing dual-currency payrolls.
The USD Priority Rule
When employees earn both USD and ZWG:
The payroll system must:
Step 1
Apply the global ceiling to USD earnings first.
Step 2
Determine any remaining ceiling.
Step 3
Convert remaining ceiling into ZWG using the official interbank rate.
Step 4
Apply NSSA to the allowable ZWG amount only.
This is commonly known as the:
“USD First Principle”
ASSUMPTIONS USED IN ALL EXAMPLES
| Item | Value |
|---|---|
| NSSA Ceiling | USD 700 |
| Employee POBS Rate | 4.5% |
| Employer POBS Rate | 4.5% |
| Total POBS Rate | 9% |
| Exchange Rate | 25 ZWG/USD |
| Sample APWCS Rate | 1% (Illustrative Only) |
Note: Actual APWCS rates depend on the employer’s industry code.
SCENARIO 1 – TOTAL EARNINGS BELOW THE CEILING
Employee Earnings
| Currency | Earnings |
|---|---|
| USD | 400 |
| ZWG | 2,800 |
Ceiling Test
ZWG equivalent:
2,800 ÷ 25
= USD 112
Combined Earnings:
USD 400 + USD 112
= USD 512
Since USD 512 is below USD 700:
No capping required.
POBS Calculation
Employee Deduction
USD
400 × 4.5%
= USD 18.00
ZWG
2,800 × 4.5%
= ZWG 126.00
Employer Contribution
USD
USD 18.00
ZWG
ZWG 126.00
Total POBS Remittance
| Currency | Employee | Employer | Total |
|---|---|---|---|
| USD | 18.00 | 18.00 | 36.00 |
| ZWG | 126.00 | 126.00 | 252.00 |
APWCS Calculation
Unlike POBS:
No ceiling allocation is required.
Assuming APWCS rate = 1%
USD Wage Bill
400 × 1%
= USD 4.00
ZWG Wage Bill
2,800 × 1%
= ZWG 28.00
APWCS Employer Premium
| Currency | Wage Bill | APWCS Rate | Premium |
|---|---|---|---|
| USD | 400 | 1% | USD 4.00 |
| ZWG | 2,800 | 1% | ZWG 28.00 |
Total Employer Cost
| Item | USD | ZWG |
|---|---|---|
| POBS Employer | 18.00 | 126.00 |
| APWCS | 4.00 | 28.00 |
| Total Employer Liability | 22.00 | 154.00 |
SCENARIO 2 – CEILING PARTIALLY CONSUMED BY USD
Employee Earnings
| Currency | Earnings |
|---|---|
| USD | 500 |
| ZWG | 8,000 |
Ceiling Allocation
Ceiling
USD 700
Less USD Salary
USD 500
Remaining Ceiling
USD 200
Convert Balance to ZWG
USD 200 × 25
= ZWG 5,000
Compare With Actual ZWG
| Description | Amount |
|---|---|
| Actual ZWG | 8,000 |
| Maximum Insurable ZWG | 5,000 |
| Excess Ignored | 3,000 |
POBS Calculation
USD
500 × 4.5%
= USD 22.50
ZWG
5,000 × 4.5%
= ZWG 225.00
Employer Match
USD
USD 22.50
ZWG
ZWG 225.00
Total POBS Remittance
| Currency | Employee | Employer | Total |
|---|---|---|---|
| USD | 22.50 | 22.50 | 45.00 |
| ZWG | 225.00 | 225.00 | 450.00 |
APWCS Calculation
APWCS normally follows the wage bill rather than the POBS insurable earnings cap.
Therefore:
USD Wage Bill
500 × 1%
= USD 5.00
ZWG Wage Bill
8,000 × 1%
= ZWG 80.00
Important Observation
POBS ignored:
ZWG 3,000
However:
APWCS may still assess the full:
ZWG 8,000
because APWCS is a separate scheme.
SCENARIO 3 – USD SALARY EXACTLY REACHES THE CEILING
Employee Earnings
| Currency | Earnings |
|---|---|
| USD | 700 |
| ZWG | 12,000 |
Ceiling Allocation
| Item | Amount |
|---|---|
| Ceiling | USD 700 |
| USD Salary | USD 700 |
| Remaining Ceiling | USD 0 |
ZWG Allocation
0 × 25
= 0 ZWG
POBS Calculation
USD:
700 × 4.5%
= USD 31.50
ZWG:
0
Employer Contribution
USD 31.50
ZWG 0
POBS Remittance
| Currency | Employee | Employer | Total |
|---|---|---|---|
| USD | 31.50 | 31.50 | 63.00 |
| ZWG | 0.00 | 0.00 | 0.00 |
APWCS Calculation
Because APWCS is independent:
USD
700 × 1%
= USD 7.00
ZWG
12,000 × 1%
= ZWG 120.00
Key Compliance Point
Even though:
ZWG POBS = 0
APWCS may still be payable on:
ZWG 12,000
SCENARIO 4 – USD SALARY EXCEEDS THE CEILING
Employee Earnings
| Currency | Earnings |
|---|---|
| USD | 850 |
| ZWG | 12,000 |
Ceiling Application
Only:
USD 700
is insurable.
Excess:
USD 150
ignored.
Remaining Ceiling
700 − 700
= 0
ZWG Allowance
0 × 25
= 0
Entire ZWG excluded from POBS.
POBS Calculation
Employee
700 × 4.5%
= USD 31.50
Employer
700 × 4.5%
= USD 31.50
POBS Remittance
| Currency | Employee | Employer | Total |
|---|---|---|---|
| USD | 31.50 | 31.50 | 63.00 |
| ZWG | 0.00 | 0.00 | 0.00 |
APWCS Calculation
APWCS may still be calculated on:
| Currency | Wage Bill |
|---|---|
| USD | 850 |
| ZWG | 12,000 |
Assuming 1%:
USD
850 × 1%
= USD 8.50
ZWG
12,000 × 1%
= ZWG 120.00
Payroll System Logic (For Software Developers)
Step 1:
Insurable USD = MIN(USD Earnings, Ceiling)

Step 2:
Remaining Ceiling = Ceiling - Insurable USD

Step 3:
Max ZWG = Remaining Ceiling × Exchange Rate

Step 4:
Insurable ZWG = MIN(Actual ZWG, Max ZWG)

Step 5:
POBS Employee = Insurable Earnings × 4.5%

Step 6:
POBS Employer = Insurable Earnings × 4.5%

Step 7:
APWCS = Gross Wage Bill × Industry Risk Rate
NSSA Portal Reporting Requirements
For every employee the payroll system should maintain:
POBS Fields
- Actual USD Earnings
- Insurable USD Earnings
- Employee USD Contribution
- Employer USD Contribution
- Actual ZWG Earnings
- Insurable ZWG Earnings
- Employee ZWG Contribution
- Employer ZWG Contribution
APWCS Fields
At employer level:
- Total USD Wage Bill
- Total ZWG Wage Bill
- Industry Risk Rate
- APWCS Premium
The Most Important Compliance Rule
The most common payroll mistake is assuming that once the employee reaches the USD 700 ceiling, all NSSA liabilities stop.
This is incorrect.
The correct position is:
| Scheme | Ceiling Applies? | Employee Pays? | Employer Pays? |
|---|---|---|---|
| POBS | Yes | Yes | Yes |
| APWCS | Generally No Individual Employee Ceiling Test | No | Yes |
Therefore:
A ZWG salary component may attract zero POBS contributions while simultaneously remaining fully exposed to APWCS premiums.
This distinction is essential for payroll accuracy, NSSA compliance audits, ERP configuration, payroll software design, and monthly NSSA return submissions.

Anita Jawali
Third Planner creates clear, practical educational lessons designed to turn business and finance concepts into usable skills.